The Florida Panhandle: Pensacola to Port St. Joe
Florida Panhandle public adjustersHurricane Isaias claims
From Pensacola and Perdido Key east through Navarre, Destin, 30A, Panama City Beach and Mexico Beach to Port St. Joe, the Panhandle mixes Gulf-front condo towers, HOA communities, military-town subdivisions, rural homes and small-town main streets. Isaias hit almost all of it at once. We represent homeowners, condo boards, HOAs and commercial owners across six counties so the insurer's adjuster is not the only expert on your loss.
- Years of industry experience
- 20+
- Years of industry experience
- Policyholders helped
- 15,000+
- Policyholders helped
- Recovered for our clients
- $900M+
- Recovered for our clients
- States served
- 23
- States served
Hurricane Isaias across the Panhandle
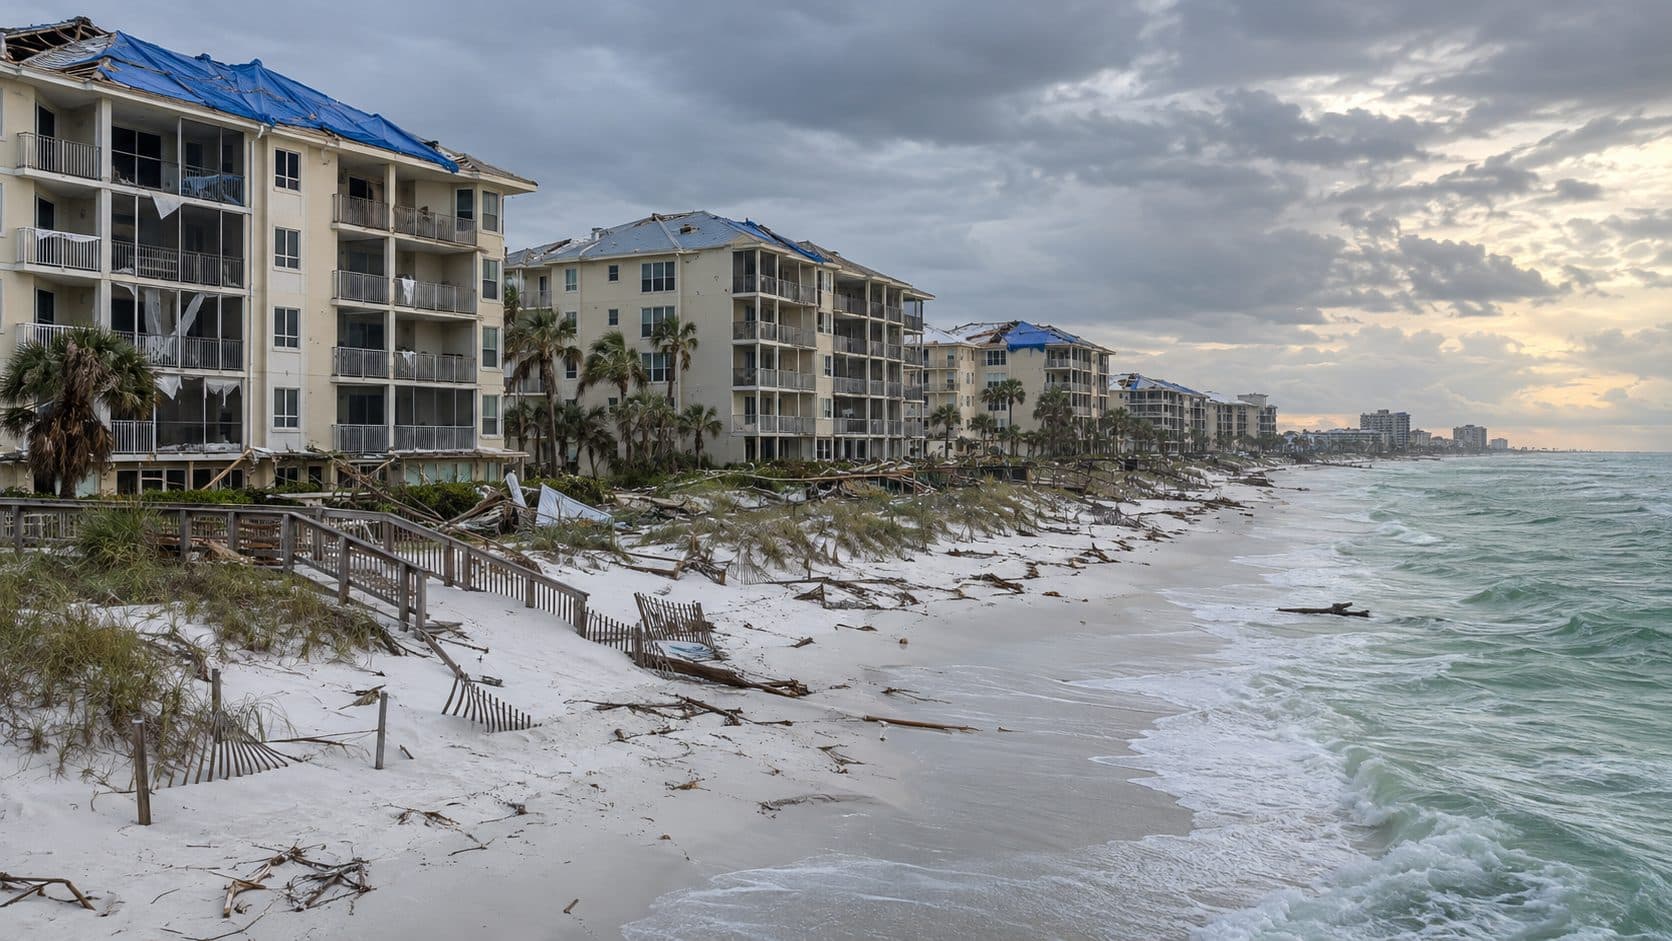
Isaias made landfall near Destin around 9:30 p.m. Eastern on October 9, 2026, as a Category 2 hurricane with 105 mph winds, with gusts to 116 mph at Santa Rosa Sound and 118 mph at Jay. The next morning 448,000 Florida accounts were without power, including 90 percent of Santa Rosa County, 85 percent of Walton, 75 percent of Escambia and 53 percent of Okaloosa, and winds had torn part of the roof off a Pensacola hotel and part of the facade off a Panama City Beach high-rise.
The first offer after a storm like this is often the lowest one. Before you accept a repair-only estimate or a denial, have someone who works for you, not the carrier, read the policy and walk the property.
The Panhandle has been here before
1995 · Hurricane Opal
Opal came ashore at Pensacola Beach as a Category 3 and left more than 1,100 major coastal structures heavily damaged between Escambia and Wakulla counties.
2004 · Hurricane Ivan
Ivan landed just west of Gulf Shores, Alabama, as a Category 3, driving 10 to 15 feet of surge from Destin west, collapsing part of the I-10 bridge over Pensacola Bay and essentially leveling Perdido Key.
2018 · Hurricane Michael
Michael hit Mexico Beach and Tyndall Air Force Base as a Category 5 with 160 mph winds, damaging more than 45,000 structures in Bay County alone.
2020 · Hurricane Sally
Sally crawled ashore with 105 mph winds and 1 to 2.5 feet of rain in many places, flooding downtown Pensacola streets and pushing the Shoal River near Crestview into major flood stage.
What we’re watching on Panhandle claims
Wind versus surge
From Pensacola Beach to Panama City Beach, Isaias brought both hurricane winds and storm surge, and insurers will try to call mixed damage flood. Roof, window, facade and wind-driven rain damage is a wind claim, flood is a separate policy, and we document each so one is not used to deny the other.
Condo roofs, reserve studies and milestone reports
Post-Surfside laws require condo buildings three stories and up to have milestone inspections and structural integrity reserve studies that cover roofs, waterproofing, windows and doors. Insurers may cite those reports to call damage old wear; we use them to prove pre-storm condition.
Hurricane deductibles and Citizens flood rules
Florida hurricane deductibles of 2, 5 or 10 percent of the dwelling limit apply once per calendar year, so a complete scope matters. If you are with Citizens, its personal residential policies with wind coverage are being phased into a flood insurance requirement that reaches all of them by January 1, 2027.
Properties we handle across the Panhandle
- Gulf-front condominium towers and resort hotels
- Condo associations and HOA communities
- Single-family homes and vacation rentals
- Apartment and multi-family buildings
- Commercial, retail and church buildings
Flood and surge: Homeowners, condo and wind policies typically exclude flood, so surge and rising water are covered only by an NFIP or private flood policy, and a new NFIP policy generally takes 30 days to take effect. Citizens personal residential policies with wind coverage must carry flood insurance by January 1, 2027.
Where we're working
- Pensacola and Perdido Key
- Gulf Breeze and Pensacola Beach
- Navarre and Milton
- Fort Walton Beach and Okaloosa Island
- Destin and Niceville
- Crestview
- Santa Rosa Beach and 30A
- Panama City Beach
- Panama City, Lynn Haven and Callaway
- Mexico Beach and Port St. Joe
Repairs and permits
Permanent repairs usually need a permit. Your local office: Your city or county building department (listed on each city page); verify any contractor's license with Florida DBPR. Keep every repair and mitigation receipt for the claim.
How it works
- 1
Call or send it in
Tell us about the property and what the carrier has said so far. A licensed public adjuster calls you back.
- 2
We review the policy
We read the policy, the carrier's estimate and any denial letter with you. Claim review at no upfront cost.
- 3
We build and fight the claim
We document the full loss, write the estimate, meet the carrier's adjusters and engineers, and negotiate.
- 4
You get paid
Our fee comes only out of what we recover. On homeowner and condo unit-owner claims from Isaias, Florida caps it at 10%.
Condo or HOA board? Read the board member hurricane checklist. Roofer with a denied job? Start here.
Panhandle claim questions
Which counties are covered by the Isaias emergency declarations?
The governor's state of emergency and the federal emergency declaration both cover Escambia, Santa Rosa, Okaloosa, Walton, Bay and Gulf counties, along with much of North Florida. For homeowners and condo unit-owner policies, that state declaration is what triggers Florida's 10 percent cap on public adjuster fees for claims made within a year after it.
How long do I have to file an Isaias claim?
Florida requires notice of a new or reopened claim within one year of the date of loss, and for a hurricane the date of loss is the landfall date, October 9, 2026. Supplemental claims have 18 months. Condo owners claiming loss assessment coverage have until the later of one year after the loss or 90 days after the board votes the assessment, but no more than three years.
Do I need a public adjuster, or can I handle the claim myself?
You can always handle it yourself, and a simple claim with a fair offer may not need help. A public adjuster makes sense when the damage is large or mixed between wind and water, when you are a condo board or commercial owner, or when the insurer's estimate does not match what contractors are telling you. There's no upfront cost to review your claim, and we're paid only from what we recover.
Sources
- https://www.foxweather.com/weather-news/deadly-isaias-start-finish-trail-destruction-gulf-coast
- https://weartv.com/news/local/governor-ron-desantis-to-address-hurricane-isaias-damage-recovery-as-panhandle-wakes-to-outages-flooding-landfall-
- https://news4jax.com/weather/2026/10/10/desantis-gives-update-after-isaias-slams-the-florida-panhandle-leaving-many-without-power
- https://baynews9.com/fl/tampa/ap-online/2026/10/10/isaias-weakens-but-flooding-threat-persists-as-hundreds-of-thousands-grapple-with-power-outages
- https://www.bostonglobe.com/2026/10/10/nation/4-dead-storm-isaias-brings-threat-floods-across-southeast/
- https://thenationaldesk.com/news/americas-news-now/hurricane-isaias-leaves-trail-of-damage-across-florida-panhandle-hurricane-isaias-florida-panhandle-storm-damage-hurricane-aftermath-walton-county-panama-city-beach-destin-okaloosa-county-grayton-beach-miramar-beach-western-lake-scenic-highway
- https://mynews13.com/fl/orlando/news/2026/10/07/desantis-declares-state-of-emergency-in-preparation-for-tropical-storm-isaias
- https://www.fox10tv.com/2026/10/10/president-trump-approves-florida-emergency-declaration-following-hurricane-isaias-fema-says/
- https://www.aoml.noaa.gov/hrd/prelim/Opal_prelim.html
- https://floridadep.gov/sites/default/files/ComparativeAnalysisDennis-etal-NWFlorida.pdf
- https://www.nhc.noaa.gov/data/tcr/AL092004_Ivan.pdf
- https://www.nhc.noaa.gov/data/tcr/AL142018_Michael.pdf
- https://www.wagmtv.com/2020/09/17/after-sally-rescue-recovery-and-a-wary-eye-on-rivers
- https://weartv.com/news/local/river-flooding-to-continue-into-weekend-for-northwest-florida
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0626/Sections/0626.854.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.70132.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.701.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0500-0599/0553/Sections/0553.899.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0700-0799/0718/Sections/0718.112.html
- https://www.citizensfla.com/flood
- https://www.fema.gov/flood-insurance
Request a claim review
Tell us what happened. A licensed public adjuster will call you back to talk through your policy, your loss and where your claim stands. There’s no upfront cost to review your claim.
Rather talk now?(850) 750-7536Good to have handy
- Your policy number, and the claim number if you have one
- Photos or video of the damage
- Any letters, estimates or offers from the carrier
Don’t have them yet? Send the form anyway.
Our fee is a percentage of what we recover, set out in your contract and capped by your state’s law. No upfront cost to review your claim.