Navarre & Navarre Beach
Public adjuster in NavarreHurricane Isaias claims
Navarre is really two places: Gulf-front condos and elevated beach homes on Navarre Beach, and the mainland subdivisions and U.S. 98 businesses across Santa Rosa Sound. Beach properties live with wind, surge and salt, while mainland homes deal with roofs, trees and heavy rain. We handle both, for individual owners and for condo and HOA boards.
- Years of industry experience
- 20+
- Years of industry experience
- Policyholders helped
- 15,000+
- Policyholders helped
- Recovered for our clients
- $900M+
- Recovered for our clients
- States served
- 23
- States served
Hurricane Isaias in Navarre
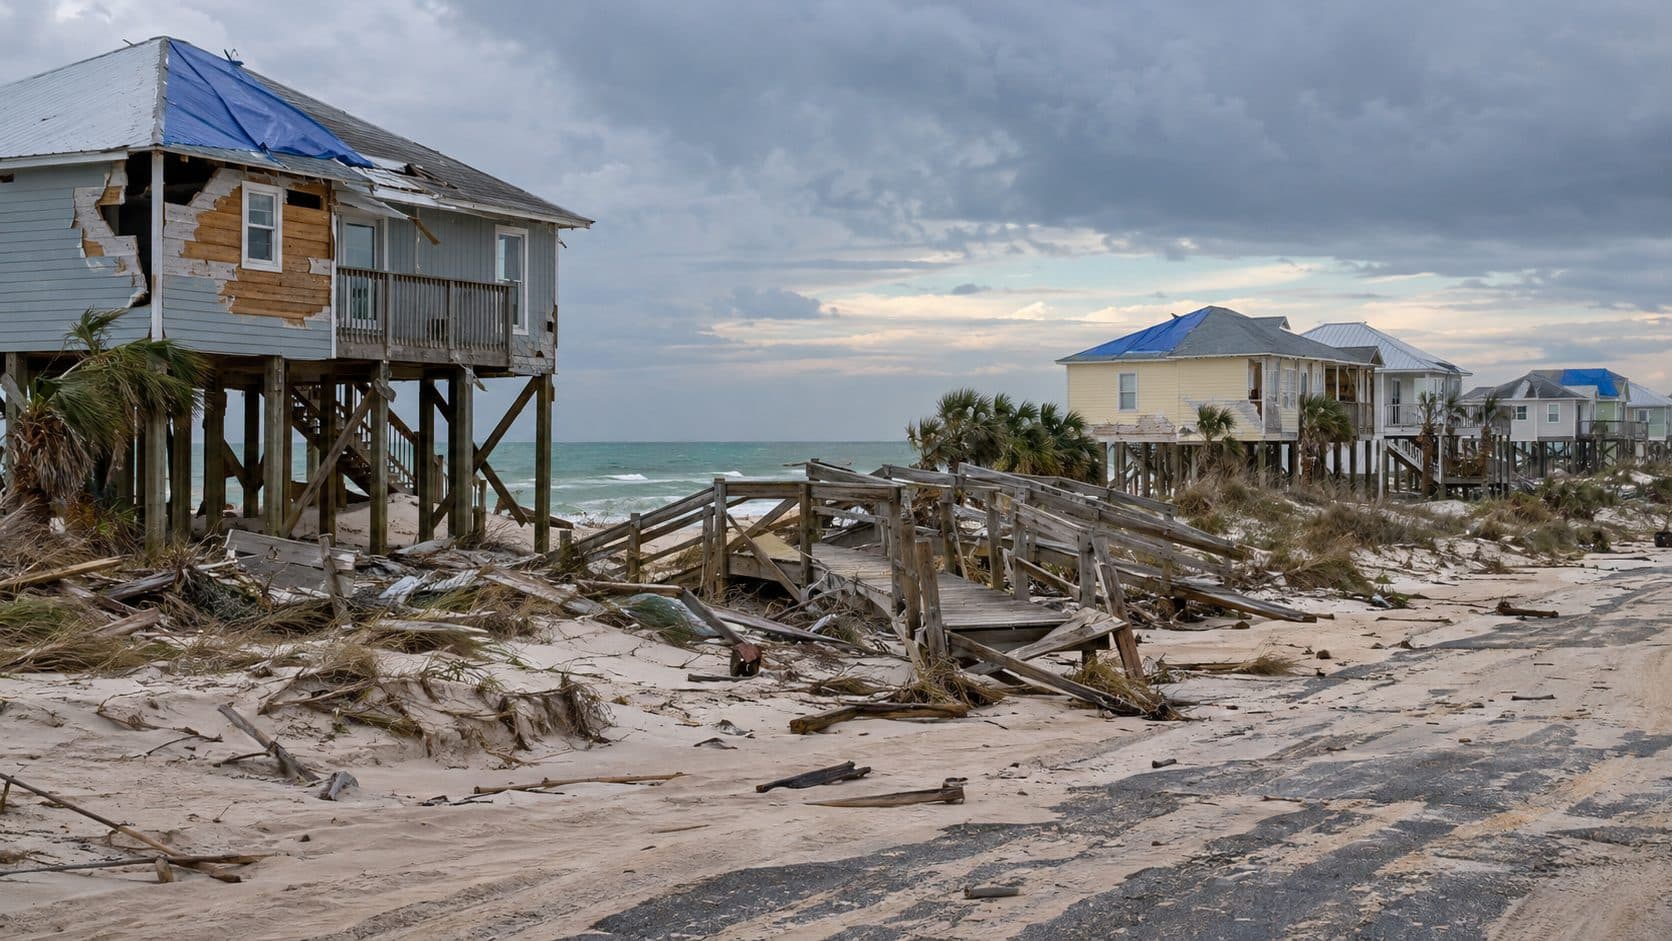
Navarre sat west of Isaias's landfall near Destin. The Navarre Beach fire chief saw no structural failures on the island but reported damage to roofs, siding and garage doors and said some homes would not be habitable, while the mainland saw flooded streets and parking lots, at least one roof blown off and a boat left on a road. Santa Rosa County peaked at about 90 percent of customers without power, and the county asked people to stay off Navarre Beach until utilities were restored.
The first offer after a storm like this is often the lowest one. Before you accept a repair-only estimate or a denial, have someone who works for you, not the carrier, read the policy and walk the property.
Navarre has been here before
1995 · Hurricane Erin
Erin's second landfall was on Santa Rosa Island at the west end of Navarre Beach, pushing a 6 to 7 foot surge across western Navarre Beach.
1995 · Hurricane Opal
Opal drove a 10 to 15 foot surge from Navarre Beach east to Destin and destroyed most Gulf-facing homes along that stretch.
2004 · Hurricane Ivan
Ivan left the Navarre Beach Causeway with significant structural damage, and it stayed closed to cars until Nov. 3, 2004.
2005 · Hurricane Dennis
Dennis made landfall near Navarre Beach as a Category 3; a gauge near the Navarre Bridge logged a 121 mph gust and almost every structure on Navarre Beach was damaged.
What we’re watching on Navarre claims
Surge vs. wind on the island
Navarre Beach homes took wind damage to roofs, siding and garage doors while surge pushed water across low areas. Your wind policy and your flood policy will each point at the other, so causation has to be documented before cleanup erases the evidence.
Homes that are not livable
When a covered loss makes a home unlivable, most homeowners and condo unit policies include loss-of-use coverage for added living costs. Keep every hotel, rental, meal and mileage receipt from the day you left.
Garage doors, siding and the hurricane deductible
On their own, a garage door and some siding can fall under a 2 or 5 percent hurricane deductible. Bundled with roof, soffit, interior and fence damage in one complete estimate, the same claim often clears it, and Florida applies the hurricane deductible once per calendar year with the same insurer (s. 627.701).
Properties we handle in Navarre & Navarre Beach
- Gulf-front condo towers and vacation rentals on Navarre Beach
- Elevated single-family beach homes on Santa Rosa Island
- Mainland subdivisions such as Holley by the Sea
- Shopping centers, restaurants and offices along U.S. 98
Flood and surge: Unincorporated Santa Rosa County, which includes Navarre and Navarre Beach, is a CRS Class 5 community with a 25 percent NFIP discount in high-risk zones, on flood maps effective Nov. 19, 2021. Surge on Navarre Beach is a flood loss, so an NFIP or private flood claim, with the standard NFIP 60-day proof-of-loss requirement, runs separately from your wind claim.
Areas we serve around Navarre
- Navarre Beach
- Mainland Navarre along U.S. 98
- Holley
- Holley by the Sea
- East Bay River area
- Santa Rosa Sound waterfront
- ZIP 32566
Repairs and permits
Permanent repairs usually need a permit. Your local office: Santa Rosa County Development Services (Building Inspections). Keep every repair and mitigation receipt for the claim.
How it works
- 1
Call or send it in
Tell us about the property and what the carrier has said so far. A licensed public adjuster calls you back.
- 2
We review the policy
We read the policy, the carrier's estimate and any denial letter with you. Claim review at no upfront cost.
- 3
We build and fight the claim
We document the full loss, write the estimate, meet the carrier's adjusters and engineers, and negotiate.
- 4
You get paid
Our fee comes only out of what we recover. On homeowner and condo unit-owner claims from Isaias, Florida caps it at 10%.
Condo or HOA board? Read the board member hurricane checklist. Roofer with a denied job? Start here.
Navarre claim questions
My Navarre Beach condo has water stains after Isaias but no obvious roof hole. Is that a claim?
It can be. Wind-driven rain through windows, sliding doors, stucco cracks and roof flashing is common in Gulf-front buildings, and the damage often shows up days or weeks later. Report it now; Florida also allows supplemental claims for additional damage from the same storm for 18 months after the date of loss.
Do I have to let the insurance company's inspector in right away?
Florida requires insurer adjusters and inspectors to give you, or your public adjuster, at least 48 hours' notice before an onsite inspection, though you can waive it. Use that time to get your own photos and documentation in order and, if you have a public adjuster, to have them there.
How long does my insurer have to pay my Isaias claim?
Florida requires insurers to acknowledge a claim within 7 days, complete any physical inspection within 30 days of receiving proof-of-loss statements, and pay or deny within 60 days of notice unless factors beyond their control get in the way. If those deadlines slip or the offer doesn't match the damage, that is the time to bring in a public adjuster.
Sources
- https://www.fox10tv.com/2026/10/10/navarre-gulf-breeze-residents-assess-storm-damage-hurricane-isaias/
- https://weartv.com/news/local/hurricane-isaias-leaves-santa-rosa-county-communities-facing-floods-debris-and-damage
- https://www.foxweather.com/weather-news/deadly-isaias-start-finish-trail-destruction-gulf-coast
- https://www.orlandoweekly.com/news/florida-news/officials-confirm-two-hurricane-isaias-related-deaths-in-florida/
- https://www.wuwf.org/live-updates/tropical-storm-isaias-updates
- https://en.wikipedia.org/wiki/Navarre,_Florida
- https://www.weather.gov/mob/erin
- https://www.weather.gov/mob/opal
- https://www.aaroads.com/florida/hurricane-ivan
- https://www.weather.gov/mob/dennis
- https://www.santarosa.fl.gov/149/Development-Services
- https://www.fema.gov/cis/FL.pdf
- https://www.law.cornell.edu/cfr/text/44/appendix-A(1)_to_part_61
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0626/Sections/0626.854.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.70131.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.70132.html
- http://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.701.html
Request a claim review
Tell us what happened. A licensed public adjuster will call you back to talk through your policy, your loss and where your claim stands. There’s no upfront cost to review your claim.
Rather talk now?(850) 750-7536Good to have handy
- Your policy number, and the claim number if you have one
- Photos or video of the damage
- Any letters, estimates or offers from the carrier
Don’t have them yet? Send the form anyway.
Our fee is a percentage of what we recover, set out in your contract and capped by your state’s law. No upfront cost to review your claim.